Pile-ins, payouts, and pacing pressure: the investors behind the VCs open up
By CelebUD Newsroom —
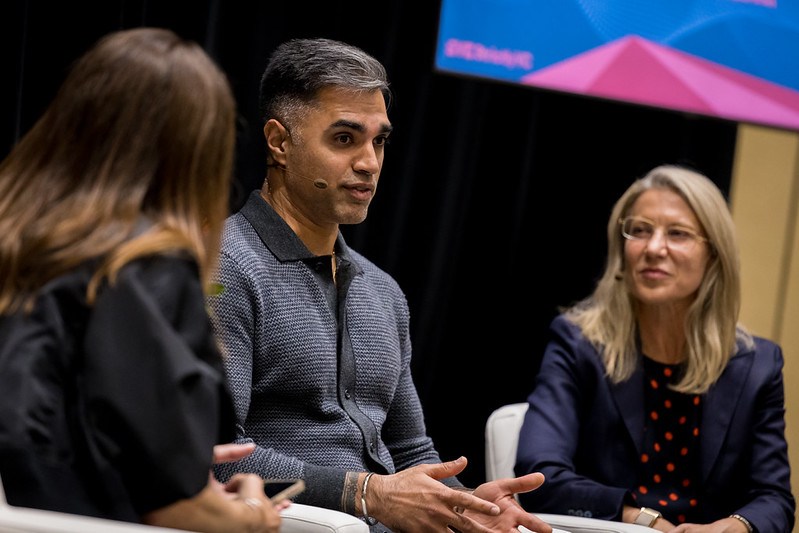
Institutional limited partners, the critical financial backers supplying capital to venture capital firms, are steering through an extraordinary period marked by unprecedented artificial intelligence valuations, aggressive fundraising cycles, and evolving liquidity mechanisms. As portfolio concentration reaches historic highs around market leaders, the institutions allocating capital are balancing the promise of massive windfalls against structural deployment risks.
Historically, the conventional limited partner playbook relied on broad diversification across multiple fund vintages, managerial profiles, and operational specialties to mitigate portfolio volatility. However, the meteoric rise of foundational artificial intelligence laboratories has upended established norms, with institutional allocators increasingly tied to overlapping mega-cap holdings across their manager rosters. Industry leaders Beezer Clarkson, partner at Zurich-headquartered multi-asset manager LGT Capital Partners, and Amit Bhatti, principal at North Carolina-based venture investment specialist TrueBridge Capital Partners, shared key perspectives on how these dynamic shifts are reshaping the asset class in 2026.
The Breakdown of Portfolio Diversification and Direct Conflicts
Venture investing has traditionally observed an unwritten rule discouraging fund managers from backing direct, head-to-head competitors within the same operational vintage. In the current market, that boundary has largely vanished as managers pile into parallel investments across major artificial intelligence labs such as OpenAI and Anthropic. Limited partners find their underlying exposure heavily concentrated in identical balance sheets regardless of how many individual funds they back.
Rather than resisting this development, institutional investors view the concentration as an accelerated manifestation of the fundamental economic law underpinning venture capital.
"Venture has always been a power law business, so I actually view the concentration as a good thing. If we were getting to the maturity of one of our funds and there were still lots of tiny positions, something’s gone wrong."
— Amit Bhatti, TrueBridge Capital Partners
Bhatti pointed out that mature vintages naturally winnow down into concentrated positions over a decade, citing established holdings such as SpaceX, Stripe, and Databricks. While early-stage vehicles still retain broader portfolio diversity with smaller capital commitments, late-stage allocations have rapidly crystallized around a tight cluster of frontier tech developers.
Deployment Pacing and Fund Upsizing Triggers
The pace at which venture firms deploy capital and return to the market for follow-on commitments has accelerated dramatically. Traditional investment horizons that typically spanned three to four years narrowed first to 24 to 36 months, and now regularly compress into rapid 12-to-18-month cycles. Some managers are attempting to raise subsequent vehicles within a single year.
This aggressive cadence creates substantial friction for endowments, foundations, and institutional asset managers that structure multi-year capital deployment schedules.
| Metric / Operational Practice | Historical Industry Norm | Current Market Dynamic |
|---|---|---|
| Fund Deployment Cycle | 2 to 4 years (24–48 months) | 12 to 18 months; occasional 1-year vintages |
| Seed Stage Check Sizes | Baseline baseline standards | Surging roughly 2x historical averages |
| Mid-Cycle Capital Adjustments | Rare occurrence | Frequent mid-fund size increases |
| Secondary Transactions | Distressed tool of last resort | Standard, proactive exit mechanism |
| Emerging Manager Profiles | Strictly full-time professionals | Open to active operators and young GPs |
To cope with the accelerated tempo without breaking internal budget models, limited partners frequently reduce ticket sizes—for instance, splitting an anticipated $10 million two-year commitment into a $5 million single-year tranche. Managers are also turning to mid-cycle fund expansions to absorb enlarged funding rounds rather than formally initiating entirely new fund processes. While compressed timelines raise caution flags, investors note a fundamental contrast with the zero-revenue speculative models of previous cycles: top AI-native enterprises are scaling from zero to $100 million in recurring revenue at historically unprecedented speeds.
The Emergence of Secondaries as the Third Leg of Liquidity
As startups remain private for extended horizons, the secondary market has graduated from a distressed fallback into an essential liquidity avenue sitting alongside traditional initial public offerings and corporate acquisitions. Clarkson emphasized that expecting institutional investors to wait up to two decades for public listings fundamentally conflicts with the structural mandate of the venture asset class.
Secondaries now operate actively across three distinct tiers:
- General Partner Direct Sales: Fund managers selling minor strips of mature equity to secure capital returns and lock in early fund multiples.
- Limited Partner Stake Disposals: Institutional allocators trading GP interests on secondary markets to rebalance liquidity portfolios.
- Structured Liquidity Tenders: Company-wide employee share tenders, which are actively monitored by lead institutional backers to preserve long-term operational retention.
The broader liquidity landscape in 2026 has witnessed substantial movement, including major outcomes like the Cerebras public listing, secondary distributions from SpaceX, and massive acquisitions within the developer software ecosystem, including a landmark $60 billion transaction involving Cursor alongside multiple $10 billion-plus buyout transactions.
Emerging Managers and Talent Flywheels
Despite capital pooling toward mega-funds, institutional allocators continue committing balance sheet capital to first-time and emerging general partners. Check sizes for these commitments generally start between $3 million and $5 million. Allocators have embraced flexible structures, backing operational executives who invest on the side, experienced general partners spinning out of established tier-one platforms, and young managers orchestrating student accelerator networks across top institutions like MIT, Harvard, and Stanford.
This ongoing capital circulation mirrors prior technology transformations. As liquidity flows to technical talent across leading labs like Anthropic and OpenAI, alumni are expected to seed the next generation of venture-backed software enterprises, preserving institutional concentration around established regional technology hubs.
What portfolio concentration means for diaspora investors
Many diaspora professionals looking to build long-term wealth invest in venture syndicates, tech-focused private funds, or venture-heavy retail vehicles. Historically, spreading money across three or four different venture funds guaranteed exposure to a broad variety of promising startups. Today, that diversification is largely an illusion as institutional managers crowd into the exact same frontier tech companies.
Because fund managers are actively backing direct competitors and piling into identical late-stage balance sheets, an investor holding multiple funds may simply be multiplying their risk on a handful of mega-cap AI laboratories. If those specific firms face valuation adjustments or regulatory headwinds, the impact hits across every vehicle at once. While these top companies are generating revenue at historic speeds, overlapping exposure removes the safety net that portfolio diversification was supposed to provide.
Before committing personal capital to another tech fund or investment syndicate, ask yourself: Have you audited the underlying assets of your current holdings to ensure you are not paying multiple management fees for exposure to the exact same companies?
Conclusion
The venture ecosystem is undergoing a generational reset where historical guidelines governing fund deployment, investment pace, and exit pathways have been rewritten. While the intense concentration in high-valuation generative computing platforms exposes institutional allocators to real downside risk if industry expectations stall, the underlying commercial revenues provide structural support rarely seen in prior speculative runs. Looking forward, the institutional focus will increasingly center on capital discipline, aggressive liquidity harvesting through secondary markets, and the selective backing of agile managers capable of capturing the next wave of technological transformation.
Reporting based on coverage by TechCrunch.
Category: Technology